overview
- Broadcom shares fell 2.69% before recovering to around $390, helped by a $200 billion partnership with Samsung to boost AI infrastructure.
- The partnership will focus on advanced memory products and semiconductor technology, strengthening Broadcom’s position in the AI chip market.
- Despite strong AI revenue growth and a solid financial outlook, Broadcom faces risks related to technological resistance and hyperscaler spending.
- The stock’s performance is closely related to the future earnings of major cloud providers, which could impact investor sentiment and growth expectations.
Broadcom stock fell 2.69% before rebounding toward $391 overnight. That’s because while a planned $200 billion partnership with Samsung strengthens the company’s AI growth story, technological resistance and hyperscaler spending risks made investors wary.
Partnership with Samsung expands Broadcom’s AI chip ambitions, AVGO stock tests $390
Broadcom shares are on track to regain the key $390 level after a volatile week, buoyed by an expanded semiconductor partnership with Samsung Electronics and renewed optimism around demand for artificial intelligence infrastructure.
AVGO fell $10.55, or 2.69%, to $381.92 on Friday, but rebounded by 2.29% to around $390.65 in overnight trading.
The pushback follows news that Broadcom and Samsung intend to expand their strategic partnership in memory, foundry manufacturing and advanced semiconductor packaging. The agreement is expected to cover more than $200 billion in business over the five years to 2030.
The scale of this partnership strengthens Broadcom’s position as one of the most important suppliers of custom AI processors and networking technology. However, the stock remains well below June’s all-time high, and the technical picture suggests buyers still need to overcome significant resistance.
Partnership with Samsung strengthens Broadcom’s AI supply chain
Broadcom and Samsung have signed a memorandum of understanding aimed at supporting next-generation artificial intelligence infrastructure.
Under the proposed partnership, Samsung would provide advanced memory products, including high-bandwidth memory, for Broadcom’s future AI accelerators. HBM has become a critical component of AI systems because it allows processors to move vast amounts of data more efficiently.
The partnership also includes Samsung’s sub-2 nanometer manufacturing technology for Broadcom-designed products, including wireless broadband communications solutions.
Advanced packaging is also an important part of the deal. Samsung and Broadcom will work on 2.3D and 2.5D integration technologies aimed at combining memory, logic and other components in increasingly complex AI systems.
This end-to-end relationship could help Broadcom secure access to some of the most constrained parts of the semiconductor supply chain.
The demand for AI processors is putting pressure on advanced memory, cutting-edge manufacturing and packaging capabilities. A long-term partnership with Samsung could provide further supply visibility as Broadcom’s hyperscale customers expand their custom chip deployments.
Broadcom’s custom AI strategy gains momentum
Broadcom has emerged as one of the strongest alternatives to Nvidia within the AI semiconductor market.
Rather than selling the same general-purpose accelerator to a wide range of customers, Broadcom develops application-specific processors tailored to the infrastructure and software requirements of individual cloud companies.
These custom AI accelerators, often referred to as XPUs or ASICs, can provide greater power efficiency and workload optimization for hyperscalers operating large data centers.
Broadcom currently produces custom chips with several major hyperscale customers and is working on next-generation processors with more companies. Management has indicated that the opportunity could reach $60 billion to $90 billion in fiscal 2027.
The agreement with Samsung could help Broadcom address that opportunity by combining its chip design expertise with advanced memory, foundry capabilities and packaging.
However, the memorandum does not guarantee that the entire estimated $200 billion will result in realized revenue. The final financial contribution will depend on customer demand, manufacturing execution, and the pace at which new AI processors reach mass production.
Strong AI revenue supports AVGO’s long-term story
Broadcom’s recent financial results provide evidence that demand for AI is already a major growth engine.
The company’s revenue for the second quarter of 2026 increased by approximately 20% to $16.75 billion, with AI semiconductor revenue increasing by 46% to approximately $6.1 billion.
The company also generated free cash flow of approximately $6.8 billion and reported an adjusted EBITDA margin of nearly 69%, highlighting the strength of its fabless operating model.
Unlike major cloud providers, Broadcom doesn’t need to use its own chips to build and operate data centers. Because the company designs semiconductors and relies on manufacturing partners, it can benefit from AI infrastructure spending without matching customers’ capital expenditures.
Broadcom expects third-quarter revenue of about $17.2 billion, driven by network demand, custom accelerators and infrastructure software businesses.
These numbers suggest a retreat from June highs, driven in part by broader valuation compression across AI stocks, rather than an obvious deterioration in Broadcom’s performance.
Nevertheless, rising expectations leave little room for disappointing growth.
Hyperscaler revenue will be Broadcom’s next major catalyst
Earnings from Microsoft, Meta, and Amazon could have a big impact on Broadcom stock.
All three companies are actively investing in AI infrastructure and represent customer demand that supports Broadcom’s network and custom silicon businesses.
If major cloud providers raise their capital spending plans, investors may interpret this move as evidence that demand for AI will remain strong through the remainder of 2026 and into 2027.
Broadcom provides switching chips, networking processors, and custom accelerators used to connect and operate large AI clusters. Therefore, continued increases in hyperscaler spending could strengthen several parts of the semiconductor business at the same time.
However, this relationship creates concentration risk.
Broadcom’s biggest AI opportunity relies on a relatively small group of technology companies. Decisions to reduce data center spending, delay custom chip programs, or move more design work in-house could have a significant impact on future growth expectations.
This risk is especially important because of the high valuations of stocks. Investors aren’t just looking for Broadcom to join the AI boom. They are pricing in years of rapid and profitable expansion.
VMware expands Broadcom beyond semiconductors
Broadcom’s infrastructure software business provides another significant source of revenue and cash flow.
VMware generated about $6.6 billion in revenue in its most recent quarter, while Broadcom continues to migrate enterprise customers to VMware Cloud Foundation.
The company’s new partnership with Standard Chartered demonstrates the strategic importance of this platform. The international bank plans to use VMware Cloud Foundation to modernize the infrastructure that supports operations across 54 markets.
The project aims to create a standardized private cloud environment for core banking, payments and digital services while improving security and resilience.
This relationship strengthens Broadcom’s exposure to enterprise infrastructure and provides diversification beyond the cyclical semiconductor market.
However, VMware’s transition has also raised concerns about pricing and product changes among some customers. Broadcom must prove that increasing revenue and efficiency does not come at the expense of long-term customer retention.
AVGO Technical Outlook: $390-400 remains key test
From a technical perspective, Broadcom’s 4-hour chart presents a mixed picture.
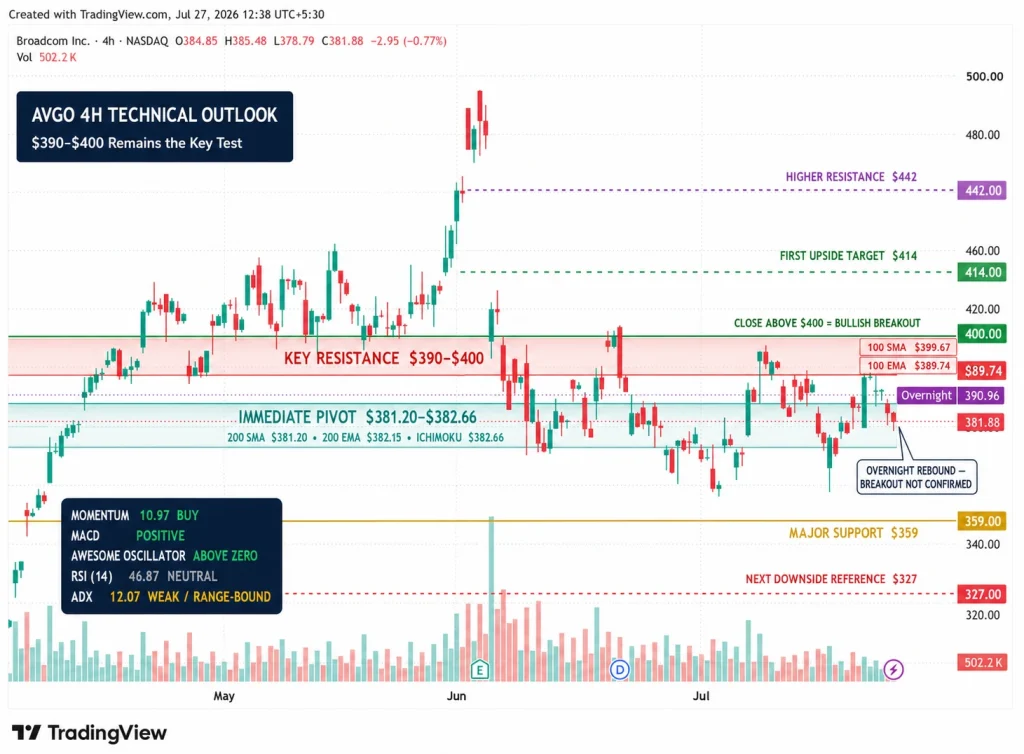
AVGO closed below most major moving averages at $381.92. The 200-period simple moving average at $381.20 provides immediate support, while the Ichimoku baseline at $382.66 and the 200-period EMA at $382.15 define the first short-term pivot area.
The overnight rally to around $390.65 pushed the stock above several short moving averages centered between $385 and $388.
However, the 100-period EMA at $389.74 points to near-term resistance, and the 100-period simple moving average near $399.67 is reinforcing the psychological $400 level.
A sustained four-hour close above $390 could improve the technical structure and allow buyers to challenge $400. A decisive move through this region could pave the way to around $414, followed by a higher resistance zone around $442.
Momentum indicators offer some encouragement. The momentum indicator is showing a buy signal at 10.97 and the MACD has also turned positive. Awesome Oscillator remains above zero.
However, the relative strength index is 46.87, indicating that buyers have not yet established clear control. The average directional index is just 12.07, indicating a weak trend and increasing the likelihood of continued range trading.
If AVGO fails around $390-$400, initial support will be around $382-$381. A decisive break below this area could expose $359 and put the broader uptrend in a more significant test. Once below $359, the next major downside will be around $327.
Broadcom stock faces serious breakout test
Broadcom’s expanded partnership with Samsung strengthens one of the semiconductor industry’s most compelling AI infrastructure stories.
Access to advanced memory, sub-2 nanometer manufacturing, and next-generation packaging could support Broadcom’s custom processors as hyperscalers build increasingly specialized AI systems.
Strong AI revenue growth, high margins, significant free cash flow, and VMware expansion provide further support.
However, an overnight stock price rebound sent AVGO directly back into a key resistance zone. Buyers need to establish a sustained break above $390 and then $400 before the technical outlook becomes definitively bullish.
For now, improving momentum suggests the possibility of further breakout attempts, but weak trend strength, hyperscaler concentration, and tight valuation expectations remain key risks.
The partnership with Samsung provides Broadcom with a strong, long-term supply chain foundation. The next test will be whether cloud spending and customer demand can grow quickly enough to justify both the size of the deal and the expectations already built into AVGO stock.

Aishwarya Gopan
Financial Writer and Editor – Asia & Europe Desk
Aiswarya Gopan is a financial journalist, editor, and content strategist with over 19 years of experience in financial markets, fintech, blockchain, and technology. She has worked with major cryptocurrency exchanges such as BingX and KuCoin to drive content strategy, market research, and editorial initiatives covering digital assets, DeFi, Web3, and global financial markets. With a background in cybersecurity, technology journalism, and market research, Aiswarya specializes in translating complex financial and blockchain developments into clear and timely insights. FX Leaders covers cryptocurrencies, stocks, forex, and macroeconomic trends in the Asian and European trading sessions.