- Everpure, Inc. previously announced that it would change its ticker symbol on the New York Stock Exchange from PSTG to P effective April 17, 2026, after an unusual fourth quarter in which revenue exceeded analyst expectations, and guidance for the next quarter also exceeded expectations.
- The company’s first multibillion-dollar revenue quarter was fueled by demand related to AI adoption, cloud expansion, and efficient data storage needs, reinforcing investor focus on recurring revenue, earnings growth, and free cash flow profile.
- Here, we examine how Everpure’s better-than-expected quarter and upbeat guidance shape the company’s broader investment story for investors.
This technology has the potential to replace computers. Discover 25 stocks that are making quantum computing a reality.
What is Everpure’s investment story?
To own Everpure, you need to believe that our AI-driven data platform can continue to translate strong sales demand into durable recurring revenue, drive revenue growth, and deliver solid free cash flow, even as broader hardware cycles change. While the rebranding and upcoming ticker change to “P” is largely cosmetic, it comes on the heels of an unusual first-ever $1 billion quarter and upbeat guidance that reinforces near-term catalysts centered around running AI, cloud, and storage workloads. Expectations are rising as the stock has recently rebounded and is trading well below both analyst estimates and discounted cash flow fair value estimates, and lower growth, margins, or cash generation could become more important. At the same time, generous earnings multiples and modest returns on equity ensure that valuation risks are taken into account.
But one new risk is that today’s high expectations could compound future disappointments. Everpure’s stock price is trending higher, but it may still be undervalued by as much as 38%. Find out what it’s worth.
explore other perspectives
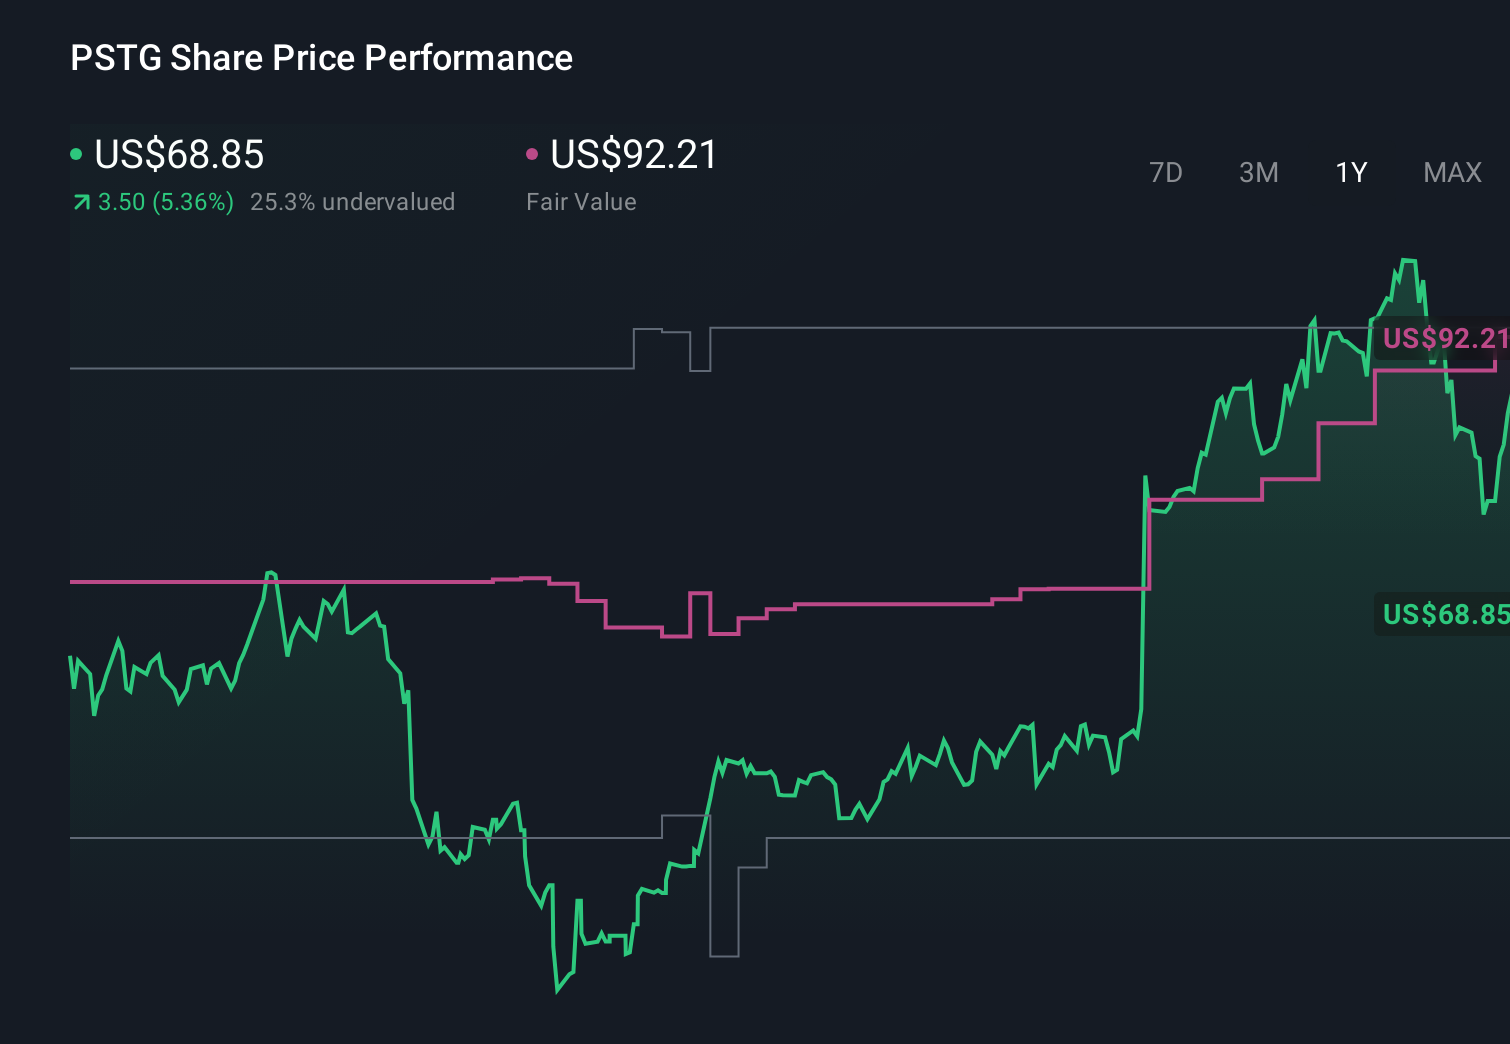
Simply Wall St Community members see Everpure’s fair value at US$84.15 to US$108.66 on 6 views, highlighting how different people think when weighing the company’s AI growth story against execution and valuation risks. Use these contrasting estimates in conjunction with recent unexpected forecasts to stress test your own expectations for the business.
Check out 6 other fair value estimates for Everpure – find out why the stock is worth 62% more than its current price.
The verdict is yours
Do you disagree with this assessment?Following the herd rarely yields exceptional investment returns. Follow your intuition.
- A great starting point for the Everpure study is an analysis that highlights four key perks that can influence your investment decision.
- Our free Everpure research report provides comprehensive fundamental analysis compiled into a single visual (snowflake), making it easy to assess Everpure’s overall financial health at a glance.
Looking for another opportunity?
At this time, our main inventory items are not attracting attention. Join early:
This article by Simply Wall St is general in nature. We provide commentary using only unbiased methodologies, based on historical data and analyst forecasts, and articles are not intended to be financial advice. This is not a recommendation to buy or sell any stock, and does not take into account your objectives or financial situation. We aim to provide long-term, focused analysis based on fundamental data. Note that our analysis may not factor in the latest announcements or qualitative material from price-sensitive companies. Simply Wall St has no position in any stocks mentioned.
Evaluation is complex, but we will simplify it here.
Discover whether Everpure is undervalued or overvalued with our in-depth analysis. Fair value estimates, potential risks, dividends, insider transactions, and financial condition.
Access free analysis
Do you have feedback on this article? Interested in its content? Please contact us directly. Alternatively, email editorial-team@simplywallst.com.