

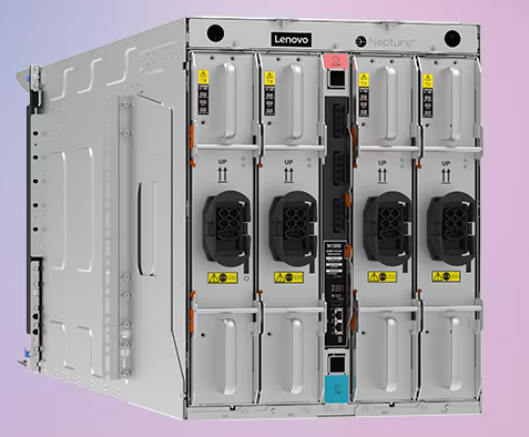
There are four businesses that make it extremely difficult for equipment manufacturers in the IT sector to make money for smartphones, PCs, data center servers and services. Also, Lenovo is one of both the biggest shippers, employing the Motorola smartphone business and IBM PC business, reducing design and manufacturing costs, making profits and doing amazing work.
However, data centers continue to be a challenge for Lenovo, and Genai Boom is making it worse, rather than better than all major OEMs pushed to narrow down some profits from this mainstream HPC hardware business. On several days, the only companies that are actually profiting from Genai Boom are Taiwan Semiconductor Manufacturing Co, which manufactures computing and switching engines, and Nvidia, where the majority of clusters supporting AI workloads are the majority of computing and networking.
But like other OEMs in the data center, Lenovo has no choice but to continue moving forward and try to add value to AI systems.
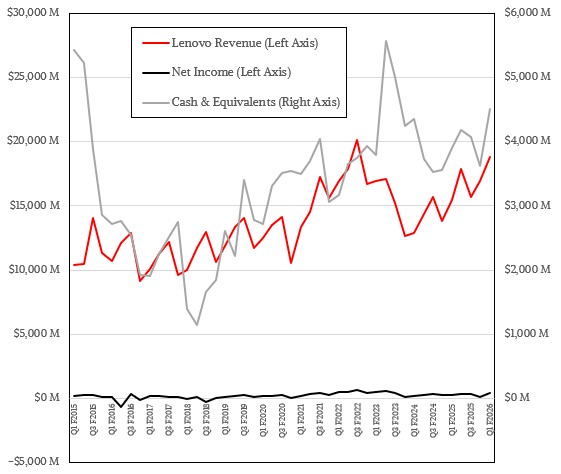
Lenovo, which ended in June in the first quarter of 2026, had sales of $18.83 billion, up 21.9% year-on-year. Total profit rose 8% to $2.77 billion, operating profit rose 59% to $785 million (I don't know why there was a big jump), and net profit rose 60.1% to $389 million. The company closed the quarter at the bank with $45.1 billion. This was the most money ever in a bank, thanks to heavy investments in research, development and manufacturing capabilities around the world, but perhaps a bit more lean than its comprehensive size.
Lenovo's Infrastructure Solutions Group acquired the System X Server and HPC Cluster business from IBM over a decade ago, so it set up a very consecutive seventh record quarter in a row, especially in China, thanks to its booming AI server business rather than its only option.
In the June quarter, Lenovo's ISG recorded sales of $42.9 billion, up 35.8% year-on-year and 4.1% from the fourth F2025. Growth is worth what Dell and Hewlett Packard Enterprise see in their respective server businesses, but thanks to the X86 server update cycle, which is a bit lagging behind by huge spending on AI servers and economic uncertainty, Lenovo is still struggling with its data center business with an operating loss of 86 million with the Q1 FF2026.

Before the fourth quarter of 2023, Lenovo had printed a chart showing the sales of data center infrastructure to cloud service providers (CSPs). I use hyperschools (someone with a huge infrastructure to run applications aimed at advertising or sub-reliant supported by cloud influencing materials (running applications aimed at customers) and cloud builders. fashion). Lenovo provided figures for the older IBM System X Business customers, Enterprises and SMB.
Since then, we have built a model that will keep this dataset alive, based on meetings with Wall Street analysts, based on what Little Lenovo says in its quarterly report. At Lenovo, Lenovo said products sold to CSPs increased 36% year-on-year, while ESMBS increased 35% year-on-year. According to our model, Lenovo's CSP division increased by 36.3% to $2.41 billion, and the ESMB division increased by 35.1% to $1.888 billion. The CSP division fell 3.7% from $2.5 billion, which was the second highest level of revenue from CSP in Lenovo's history. The ESMB division rose 16.3% as companies moved to more current X86 iron based on the latest Intel Xeon and AMD EPYC processors.
I don't know the operating profit for the CSP or ESMB division. However, Winston Cheng, Lenovo's Chief Financial Officer, said this over the phone.
“You'll probably notice that our ISG business is growing very rapidly. We've specifically revealed that AI server revenues have more than doubled from the previous year.”
“We are very familiar with the dynamics of the current AI server industry, which is the margin of this segment, so transactions will be large, but they may be slightly lower from a gross profit perspective, as they are related from the perspective of other segments of the server business, such as SMB space, or from the perspective of IDG business. You.”
Well, that's what we can do with math.
Lenovo had a gross profit of $2.77 billion on revenue of $18.83 billion. This is 14.7%. We conclude with gross profit being “17% north” and being called 17.2%. The non-CSP portion of Lenovo saw profits of $16.42 billion and about $2.82 billion. That is, the total loss for the CSP business was $50 million. Allocating all Lenovo operating expenses proportionate to revenues, the CSP division had an operating expenses of $255 million ($2,411 divided by $18,830 times the operating expenses of $1,989).

That means every $7.90 sold by Lenovo for selling CSP Iron, you lose $1.00 at the operational level, as long as it can be mostly an AI system.
This means that the ESMB division has withdrawn operating profit of $391 million. This is 20.8% of revenue. Q1 If the cost is allocated more heavily to the F2026 CSP system, the ESMB business will be even more profitable than the OUT calculation shows. ESMB Business believes it is much more profitable than Solutions & Services Group, which accounted for an average of 21.1% of its average revenue over the past five years, or Intelligent Devices Group, which accounted for 7.2% over a much larger revenue stream, with an average of 7.2% over the same period. This latter bit is how Lenovo can afford to invest in the data center business.
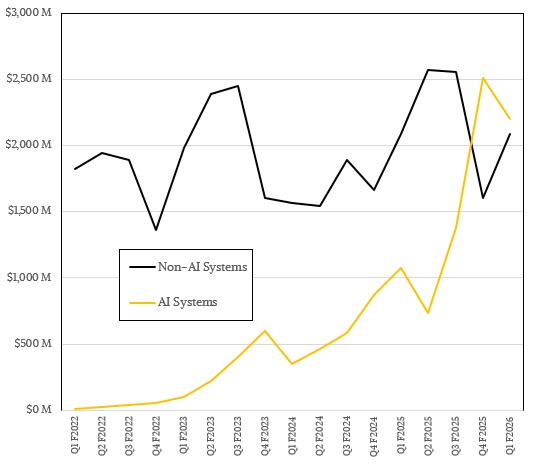
Our Lenovo model not only tracks the CSP and ESMB divisions, but also tries to split the sales of AI systems from other non-AI systems sales quarterly. Lenovo estimates that it sold under $3 billion AI systems in the first quarter at 2.8 times the previous year, up 18.7% from the $25.1 billion sold in the Q4 F2025, which ended in March. Lenovo didn't talk about the pipeline, but our best guess is that it's probably more than 1.5 times the revenues of 12 months, which have been booked so far, well above $10 billion and perhaps kissing $12 billion.
When assessing how ISG works, I think it's best to look at it every year rather than quarterly. Server spending has slowed down and is a bit choppy. Lenovo has a huge presence, and is from (US and China), and there is a trade war between the two countries where AI and HPC businesses are always choppy with low profit margins. (Again, except for certain computational engine providers, historically.)
That way you will see that Lenovo is working hard, but it really doesn't make much money from that effort.
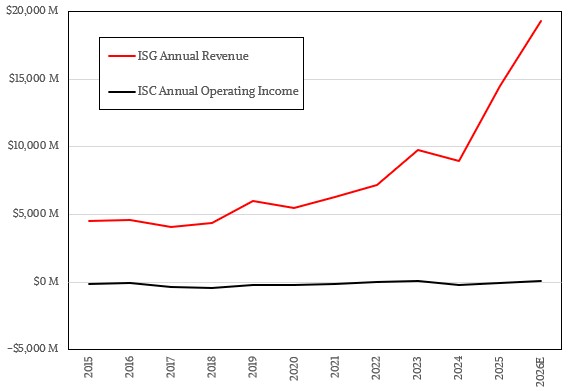
It's a tough set of curves. ISG's revenue has increased quadruple since IBM System X Takeover, but its profitability is very small and it's difficult to see.
That said, we respect Lenovo's customer tenacity in serving and are committed to ultimately making ISG profitable. There's time and savings to get there. And with Ashley Golafurwara managing various data center infrastructure businesses in Dell for 20 years, and then being appointed president of ISG in November 2024 (he won four years of stints at Western Digital before joining Lenovo), Lenovo could potentially find a profitable way to do so in data centers.
Nvidia can help by providing a little more margin to OEM partners who create infrastructure based on their computing and networking engines.


